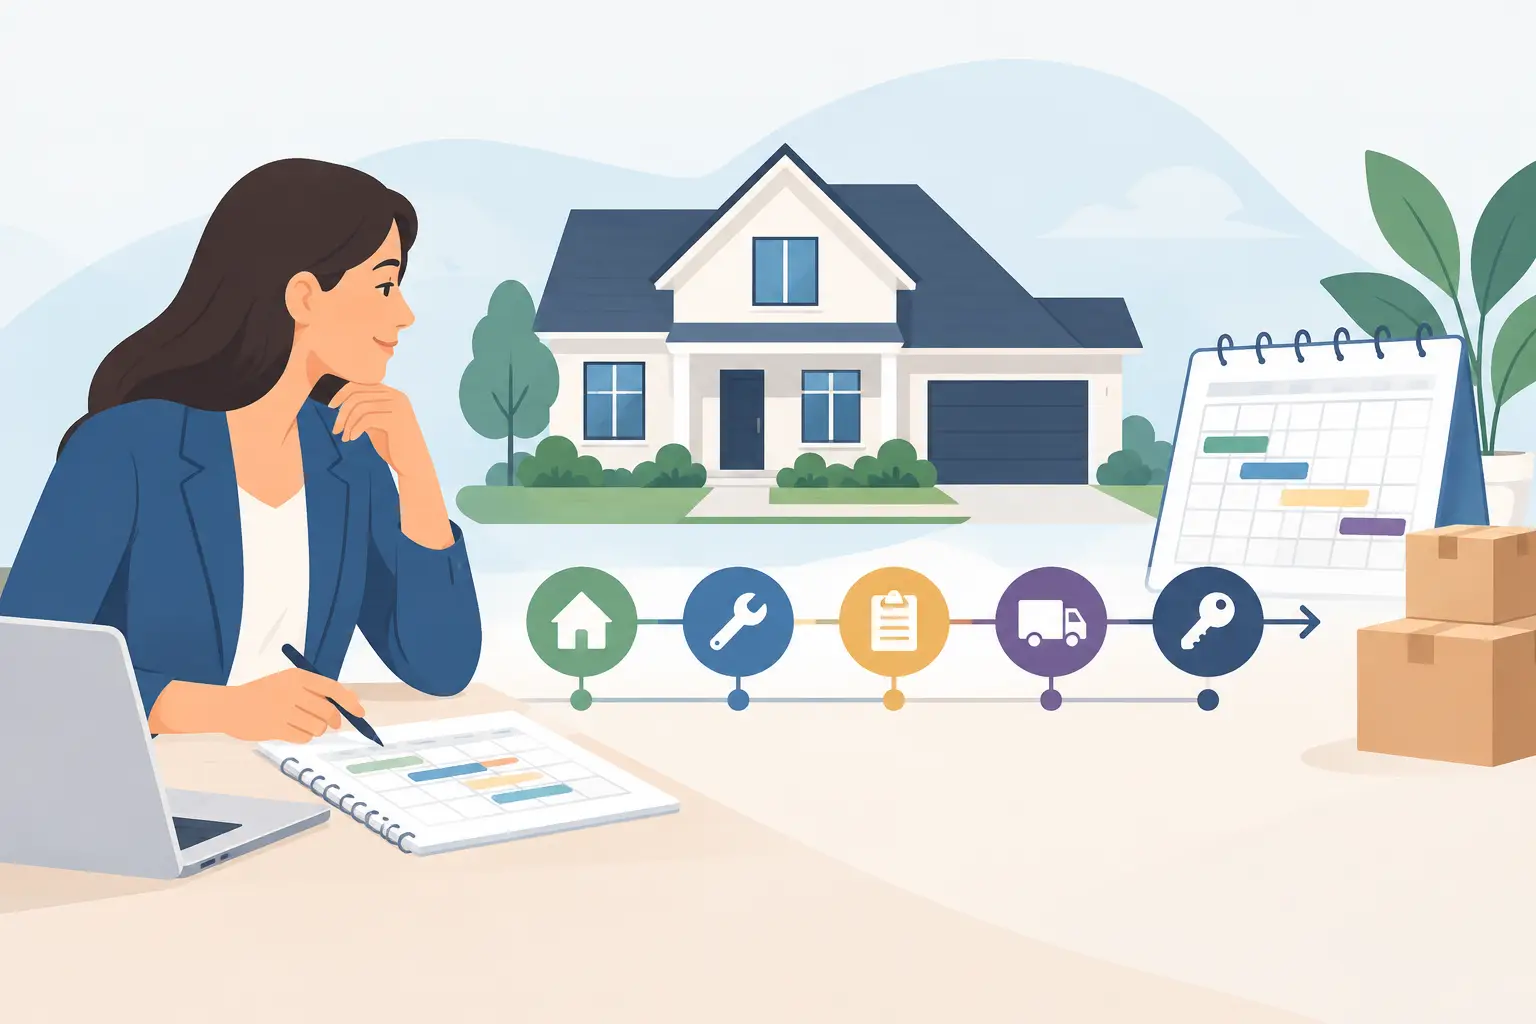
A move can look simple on a calendar: sell one home, buy another, move the boxes. In practice, the ability to coordinate home sale timeline decisions determines whether the process feels controlled or becomes an expensive scramble. For Northeast Ohio homeowners, the right sequence protects both your negotiating position and your day-to-day life.
The goal is not always to make the sale and purchase close on the same day. That can work, but it can also create unnecessary pressure. The stronger objective is to build a plan with clear decision points, realistic backup options, and enough flexibility to respond when an inspection, appraisal, lender, or buyer changes the pace.
Coordinate Your Home Sale Timeline Before You List
The most effective timelines begin before photography, staging, or a yard sign. Start with the non-negotiables: your target move date, school or work commitments, lease deadlines, travel, construction plans, and the amount of cash you may need from your current home for the next purchase.
Then assess how dependent the transactions truly are. Some sellers need sale proceeds for their down payment. Others have the liquidity to buy first, which can make their offer more appealing in a competitive neighborhood. Neither path is universally better. It depends on cash reserves, comfort with carrying two properties temporarily, and the urgency of finding the right next home.
For a distinguished property or luxury residence, preparation may require more runway. Selective repairs, strategic updates, staging consultation, cinematic photography, video production, and a custom marketing rollout cannot be rushed without sacrificing presentation. A well-prepared launch creates early buyer attention, which is often when a listing has its strongest leverage.
Build backward from the date that matters most
If you need to be settled before a new school year, a job relocation, or the end of a lease, work backward. Allow time for preparation, active marketing, contract negotiation, inspections, appraisal, financing, title work, and moving. In many transactions, a 30- to 45-day closing is common after a contract is signed, but the days before accepting an offer can vary widely.
A home that is priced and positioned well may attract serious attention quickly. Still, sellers should avoid treating a fast offer as a guaranteed finish line. The contract period is where details matter: inspection findings, financing conditions, appraisal results, title requirements, and the buyer’s own home-sale contingency can all affect timing.
Price for Leverage, Not Just for Attention
An ambitious list price can feel like a safe starting point, especially when a homeowner has invested heavily in a property. Yet pricing too far above current buyer expectations can extend market time, which can complicate the entire move-up plan. If the next purchase depends on your sale, a stale listing may reduce choices and add stress at the worst possible moment.
Strategic pricing is not about leaving money on the table. It is about creating the conditions for buyers to act. Relevant local comparables, current inventory, property condition, location, and buyer demand should shape the launch price. In Medina County and across Cuyahoga, Summit, and Lorain counties, conditions can differ sharply by neighborhood, price point, and property type.
The Ashton Advantage℠ approaches each listing as a distinct property brand, pairing precise positioning with world-class luxury marketing strategies designed to create meaningful demand. Strong exposure does not replace sound pricing, but together they can strengthen a seller’s negotiating position and shorten the period of uncertainty between listing and contract.
Decide Whether to Sell First, Buy First, or Bridge the Gap
There are three common ways to coordinate a sale and purchase. Each has benefits, and each requires a clear-eyed view of risk.
Selling first gives you clarity. You know your proceeds, understand your budget, and avoid the possibility of owning two homes longer than expected. The trade-off is that you may need a temporary place to live if the right next property does not appear before closing.
Buying first gives your household more time to move deliberately. It can be especially attractive when inventory is limited or when a specific neighborhood, school district, or home style is difficult to replace. The trade-off is financial exposure. You may need to qualify while carrying your current mortgage, make a larger down payment, or accept the cost of two homes for a period.
The middle path is a negotiated bridge. A seller may ask for a longer closing, a post-closing possession agreement, or a home-of-choice contingency. A buyer may agree, particularly when the home is compelling and the terms are reasonable. However, these provisions should never be assumed. They require thoughtful negotiation and must align with lender, insurance, and legal requirements.
Be careful with contingency chains
A buyer whose purchase depends on selling another property is not necessarily a weak buyer. Their home may already be under contract, their financing may be solid, and their timeline may fit yours well. But the chain has more moving parts. If their buyer delays or fails to close, your timeline could be affected.
Evaluate the entire picture: how far along the other sale is, whether inspection and appraisal have been completed, the buyer’s financing strength, and what contractual protections are available. The highest price is not automatically the best offer if its path to closing is uncertain.
Treat the Contract-to-Close Period as Active Work
Once the purchase agreement is signed, the work shifts from marketing to risk management. Inspections often happen early, and the resulting requests can affect both cost and timing. A measured response matters. Safety issues, major defects, and lender-required repairs deserve close attention; cosmetic requests may be negotiable.
Appraisals deserve the same discipline. If the appraisal comes in low, the buyer and seller may need to renegotiate price, adjust the down payment, challenge the value with additional market evidence, or end the transaction. A pricing strategy grounded in credible data reduces this risk, but no appraisal outcome is automatic.
During this period, do not make large purchases, change jobs, move money without documentation, or open new credit if you are also financing your next home. Buyers can be re-verified by lenders shortly before closing. Keeping your financial profile stable protects your purchasing power when it matters most.
Create a Plan B Before You Need One
A calm transaction is not one where nothing changes. It is one where everyone knows what happens if something does.
Before listing, identify a temporary housing option, even if you do not expect to use it. Consider where you could stay, how much storage would cost, and whether a short-term rental makes sense. If you are buying, decide in advance how long you are willing to search before adjusting your criteria, extending temporary housing, or changing your approach.
Also establish a communication rhythm. Weekly updates are often useful during preparation and active marketing. Once under contract, key milestones should be tracked closely: inspection completion, repair decisions, appraisal, loan commitment, title clearance, final walkthrough, and closing. Clear communication prevents small delays from becoming surprises.
Let Possession Terms Support the Move
Closing date and possession date are related, but they are not always identical. In some situations, a seller can remain in the home briefly after closing through a written post-closing possession agreement. This can create valuable breathing room for a household moving into a new home.
There are trade-offs. The agreement must address insurance, deposits, maintenance responsibilities, access, and the exact date keys will be delivered. For buyers, allowing a seller to stay may be worthwhile when it secures a desired home. For sellers, it can reduce moving pressure, but it should not become an open-ended arrangement.
The best timeline is the one that gives you room to make good decisions. Prepare early, price with discipline, evaluate offers beyond the headline number, and protect each milestone with a practical backup plan. That is how a major move becomes a well-managed transition rather than a race against the calendar.